Cash Advance – Quick Borrow

- 27.00 Reviews
- 4.8
- Downloads
- 10,000+
 Analysis by Mobxio
I would make one decision before opening Cash Advance – Quick Borrow: am I trying to compare a short-term borrowing option, or am I hoping an app will make a difficult money situation disappear? I see it as useful for the first purpose, not the second. It is a finance app from TIMECORE Studio that helps people explore cash advance and personal loan offers through an online request. That can be a practical starting point when a necessary expense cannot wait, provided I stay focused on what repayment will mean afterward.
The app is free to install and rated for Everyone, but neither fact makes borrowing free or suitable for every user. Its 4.8 average from around 942 ratings is encouraging, and over 10 thousand installs show that people have found it and tried it. At the same time, version 1.0.7 and its February 27, 2026 release make it a relatively new product. I would take the favorable reception as a reason to consider the app, not as a substitute for examining a specific offer carefully.
How Cash Advance – Quick Borrow fits into real borrowing decisions
I’d begin with the question that matters before any borrowing request: what would make an offer genuinely useful, beyond simply arriving quickly? For me, the answer is a clear repayment plan that fits the next month’s essentials, not just a convenient application. That distinction helps put Cash Advance – Quick Borrow in context and makes it easier to judge when its focused approach is worth exploring.
Start with the expense, not the offer
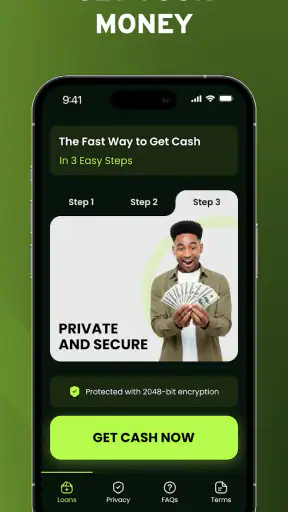
The strongest part of the experience is the way it focuses on one immediate task. Instead of opening a general budgeting suite filled with charts, savings goals, and account tools, I can use this app with a specific question in mind: what borrowing options might be available for my short-term need? That narrow purpose makes it easier to begin when I am already dealing with an urgent expense.
A realistic example would be an unexpected household repair shortly before payday. I might open the app, review the request flow, and use it to investigate possible cash advance or personal loan offers. The useful discipline is to treat the request as research first. Before accepting anything, I would write down the amount needed, the date I expect to repay it, and the maximum total repayment I can genuinely manage. That small preparation prevents the urgency of the moment from deciding everything for me.
The app’s quick online request is appealing because a mobile form can be more convenient than visiting several offices or searching through unrelated websites. Still, “fast” should describe the request process rather than guarantee that money will arrive immediately. Approval, eligibility, lender review, and transfer timing can all affect the outcome. I would never plan a rent payment around an assumption that an application must succeed.
Decide what a useful result would look like
My first practical tip is to use the app when you already know the size and purpose of the gap. Vague borrowing tends to become oversized borrowing. If the need is a specific utility bill, medical expense, or necessary repair, the request can be judged against a clear target. If I simply feel short on cash, I would pause and inspect my budget before opening a borrowing application.
More Stories to Explore
Uber Eats After the OS Update: Better Tracking, More Permission Friction
Google Chrome Wins App of the Week for Making Everyday Browsing Easier
Wordscapes Makes the Five-Minute Break Feel Complete
Switching to Audible Means Building a Listening Habit
Moovit Review: A Better Transit Guide When Your City Has the Data
Brave’s Privacy Has Limits Set by Android and iOS
A second useful workflow is to compare the requested amount with the amount that would actually be repayable. A smaller advance may solve the immediate problem while creating less pressure in the following pay cycle. Conversely, borrowing too little and then submitting another request can make the situation harder to track. I would therefore prepare one realistic estimate before entering the app rather than adjusting the figure impulsively.
The third insight is that an offer should be read in two separate ways. First, I would ask whether the repayment schedule fits my income. Then I would ask what the borrowing costs in total. A payment that looks manageable in isolation can still be expensive when fees or interest are included. The app can help me reach an offer, but the important financial judgment happens when I inspect the details and compare them with alternatives.
Where a focused request has an advantage
Compared with asking a bank directly, a focused online request can feel less intimidating and may save time at the beginning. A traditional bank, however, may be the better route for someone who already has an established relationship, understands the available products, and can qualify for a lower-cost option. I would not assume that convenience equals affordability.
Compared with borrowing from friends or family, an app-based offer is more formal and may provide a clearer repayment structure. That can protect personal relationships, but it also introduces financial charges and contractual responsibilities. For a small temporary shortfall, discussing a repayment date with someone I trust could be less costly. The trade-off is privacy, speed, and the emotional difficulty of asking for help.
Compared with a credit card or an existing overdraft facility, a personal loan offer may provide a defined repayment plan, while a cash advance can be easier to consider for a short gap. The right choice depends on the terms already available to the user. I would compare the total cost and due dates rather than choosing based on the product label alone. The most convenient borrowing option is not automatically the cheapest one.
When another route is the better fit
For an expense that can wait, I would compare borrowing with delaying the purchase, saving toward it, or asking the bill provider whether a payment arrangement is possible. Those options may take more effort, but they avoid taking on a new obligation if the timing is flexible. A credit union or an existing bank relationship may also be worth checking where available; the point is to compare real terms, not assume one kind of provider is always best.
For someone who is already behind on several payments, a new advance may make next month harder rather than solve the underlying problem. I would first list due dates, minimum payments, and essential costs, then contact creditors or seek qualified financial guidance if the budget does not balance. This app is not a debt-management service, and a new offer should not be treated as a plan for handling old obligations.
There is also a practical distinction between needing money today and needing certainty today. If a payment deadline is close, I would contact the person or company expecting payment before relying on a borrowing request. A short extension or an agreed payment date can sometimes address the immediate pressure without adding debt. The app is more relevant when borrowing is genuinely the chosen route, not simply the first action taken in a stressful moment.
Keep the application from becoming a rushed decision
The main weakness is not that the app asks users to make a request; it is that the phrase “quick borrow” can encourage rushed decisions. Financial urgency narrows attention. A person may focus on receiving money and overlook the repayment amount, recurring charges, or consequences of missing a due date. That risk exists in the user’s situation, but a fast, streamlined flow can make it easier to move too quickly.
I would also avoid treating an initial result as a final answer. An offer can depend on personal circumstances, eligibility checks, and the lender involved. Even when an application is simple to submit, the result may not match the amount or timing I hoped for. If the app presents several possibilities, I would save the relevant details separately so I can compare them calmly rather than accepting the first visible option.
One non-obvious way to slow the process down is to decide on a personal stop point before submitting anything: for example, I would not proceed if the repayment date falls before my next reliable income or if the total cost exceeds the amount I can justify for that emergency. This is more useful than deciding under pressure after an offer appears. I would also avoid making repeated requests simply because the first result disappoints me; a different amount or another application does not automatically improve affordability.
Use sensitive information deliberately
Because a loan request involves sensitive personal and financial details, I would prepare before starting. I would use a private connection, check that I am entering information into the intended application, and read each screen instead of tapping through automatically. I would also keep a record of what I submitted and review any consent or disclosure language presented during the process.
I would not enter information simply to see how much I might receive. A request should be connected to a genuine need and a repayment plan. This is especially important for younger users: the Everyone rating describes the app’s content suitability, not whether borrowing is appropriate for every person. Age suitability and financial readiness are different questions.
If I share a device with someone else, I would think about whether application details or notifications could be visible to them and take ordinary steps to protect the phone. I would also avoid sending financial information through a message or channel that is not clearly part of the request process. These habits do not decide whether an offer is good, but they reduce the chance of treating private details casually while moving quickly.
Who is likely to benefit, and who should pass
I see the best fit as an adult who has a defined, temporary cash need and wants a convenient way to investigate possible offers. Someone who is comfortable reading financial terms and comparing total repayment can use the app as an efficient first step. It may also suit a person who prefers completing an initial request on a phone rather than beginning with a branch visit or several separate searches.
The app is less suitable for anyone looking for guaranteed approval, guaranteed same-day funds, or a borrowing option without meaningful cost. It is also a poor match for someone already juggling several unpaid debts. Taking another advance in that situation can postpone the problem while increasing the pressure on future income.
I would skip it for a non-urgent purchase that can wait. Saving gradually, negotiating a payment date, using an existing low-cost facility, or comparing a credit-union product may be wiser depending on the circumstances. The app earns its place when speed and convenience matter, but those benefits should justify the search process, not override basic affordability checks.
What to check before moving from an offer to a commitment
Before accepting anything, I would look for the full repayment amount, the dates payments are due, any fees or interest, and what happens if a payment is late. I would check whether the proposed schedule leaves enough for ordinary expenses after each payment, not just whether the first instalment looks manageable. If any term is unclear, I would pause and seek an explanation rather than treating uncertainty as a minor detail.
I would also keep a simple comparison note for each option I consider: amount received, total amount repaid, payment dates, and any conditions that matter to me. Writing those down makes it easier to compare an app-based offer with a bank, card, overdraft, or payment arrangement on equal terms. It is a small step, but it prevents a polished presentation or a quick result from taking the place of a real cost comparison.
A common question is whether opening the app means money is guaranteed. I would not plan around that: a request is a way to explore possibilities, while eligibility and timing can affect what happens next. Another practical question is whether the app replaces budgeting help. I would use it for its borrowing purpose only; if the same shortage keeps returning, a budget review or debt support is the more relevant next step.
Expectations for a relatively new release
Cash Advance – Quick Borrow supports Android 7.0 and later, which makes it accessible to people using older compatible devices. I appreciate that broad device reach, particularly for users who do not replace phones frequently. At the same time, the recent release date encourages me to keep expectations realistic and check for updates before relying on the app for an urgent request.
The rating is encouraging, but I would interpret it as evidence that users generally respond well to the app, not as proof that every offer will suit every borrower. Finance apps are judged partly by usability and partly by outcomes that depend on individual circumstances. A smooth interface cannot turn an expensive loan into an affordable one.
Because the product is still early in its life, I would make sure I understand the request flow as I go rather than assuming every screen will behave like a familiar banking app. That is not a reason to dismiss it; it is a reason to keep my own notes and avoid relying on memory when comparing terms. A free download is easy to try, but the financial decision that follows deserves more time than the installation.
My recommendation depends on the repayment plan
After looking at its purpose and practical use, I would recommend Cash Advance – Quick Borrow as a starting point for people who need to explore short-term borrowing or personal loan possibilities from a mobile device. Its focused approach is easier to understand than a crowded finance app, and the free entry point removes a barrier to beginning the search. The strongest benefit is convenience: it puts the request process in one place when time feels limited.
My recommendation comes with a firm condition. I would use it to gather and compare options, then slow down before accepting anything. Check the total repayment, the schedule, the consequences of a missed payment, and whether the amount is genuinely affordable after ordinary living costs. If another route is cheaper or avoids new debt, that route deserves priority.
In short, this is a useful finance app for a specific moment, not a magic fix for an ongoing budget problem. Use it as a comparison and application starting point, never as permission to borrow beyond your means. For a clearly defined emergency and a realistic repayment plan, it may be worth trying. For recurring shortages, nonessential spending, or anyone seeking guaranteed easy money, I would choose a different solution first.
Cash Advance – Quick Borrow FAQ
What is Cash Advance – Quick Borrow, and how does it work?
Cash Advance – Quick Borrow is a financial app designed to help eligible users request short-term funds through a mobile device. After creating an account, you may be asked to provide personal, employment, and banking information so the service can review your application. If approved, the available amount, repayment schedule, fees, and other terms should be shown before you accept the offer. Approval and funding are not guaranteed.
Who can use Cash Advance – Quick Borrow?
Eligibility depends on factors such as your age, location, identity, income, employment status, banking history, and the requirements of the lending partners available through the app. Meeting the basic requirements does not necessarily mean you will be approved. Before applying, check whether the service operates in your region and carefully review its privacy policy, eligibility rules, and any information it requests during registration.
How much does borrowing through the app cost?
The total cost can vary according to the amount borrowed, repayment period, lender, and your individual offer. Possible charges may include interest, service fees, origination fees, late-payment penalties, or other costs. Do not rely only on promotional wording such as “quick” or “easy.” Review the annual percentage rate, total repayment amount, due dates, and all disclosures before accepting any advance.
How quickly will I receive the money after approval?
Funding speed depends on the application review, identity verification, banking institution, lender processing times, weekends, and the transfer method selected. Some approved requests may arrive quickly, while others can take longer or require additional documentation. The app should provide an estimated delivery time, but this is not a guarantee. Confirm the funding timeline and any expedited-transfer fee before completing the request.
Is Cash Advance – Quick Borrow safe to use?
Before using the app, verify that it is downloaded from an official app store and identify the company or lending partners operating the service. Read the privacy policy to understand how your financial and personal data may be collected, stored, or shared. Never provide passwords, verification codes, or unnecessary account access. Also check independent reviews and the loan agreement for complaints, recurring charges, and repayment risks.
The Best Parts of Cash Advance – Quick Borrow
Things to Keep in Mind About Cash Advance – Quick Borrow